
No, DraftKings is not letting you bet with Bitcoin
The name fools almost everyone. A crypto event contract is not a wager funded in cryptocurrency; it is a binary yes/no contract about the price of a cryptocurrency, usually Bitcoin, resolving at a fixed time. DraftKings is expanding into these products through DraftKings Predictions, and the company’s crypto contracts are routed through Crypto.com rather than its own DKeX exchange. CEO Jason Robins said at the NEXTPredict Summit in New York that he has softened his stance on the category after early signs of demand.
That distinction is not pedantry. It changes which regulator is in charge, which consumer protections apply, and whether the product is available where you live. The question worth asking about crypto event contracts betting is not “is it legal in my state,” which is the habit every US bettor learned after 2018. It is a different question, and most people are not asking it yet.
How a crypto event contract actually works
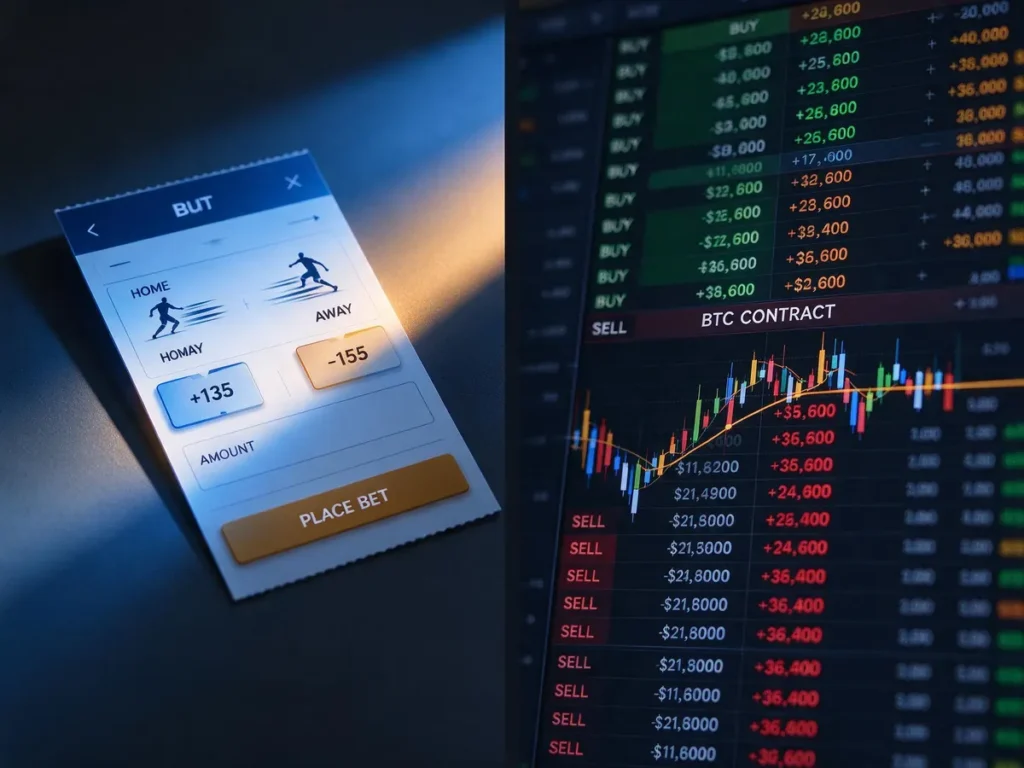
An event contract is a binary instrument with two possible end states: it settles at full value if the stated event happens, or at zero if it does not. A typical short-duration crypto market asks whether Bitcoin will be above a given price at a given minute. You buy or sell the contract at a price that functions as an implied probability, and at expiry the contract resolves against a reference price.
Pricing, settlement and payout
Three mechanical differences separate this from a bet slip. First, nobody at DraftKings sets a price the way a trading team sets a moneyline; the price moves with order flow between participants on an exchange. Second, you can usually sell your position before expiry at whatever the market will pay, rather than accepting a cash-out figure the operator chooses to offer. Third, the operator’s revenue comes from trading and settlement fees rather than a built-in margin on the odds.
On the “crypto” part of the payout, be careful what you assume. These are contracts on crypto prices, and nothing in DraftKings’ announcement establishes that settlement runs on blockchain rails or pays out in stablecoins. The Crypto.com routing is a venue relationship. Eilers & Krejcik Gaming analyst Brad Allen, quoted in Casino.org’s reporting on Robins’ comments, noted DraftKings may be looking at bringing that volume in house later.
Why DraftKings is moving now, and what it is really hedging
Two motives, and the second one matters more. The first is straightforward demand. Allen’s figures put short-duration crypto contracts, the 15-minute and daily markets, at roughly 90% of Execution Volume on the largest US prediction market, and about 9% of Polymarket’s US volume on a trailing 30-day basis, with Polymarket having only recently launched those markets and now offering five-minute Bitcoin contracts. One estimate cited in the same reporting has volume on timed crypto derivatives up 44 times over the first seven months of 2026, and that happened while major crypto prices were flat to falling.
The second motive is regulatory insurance. Robins pointed out that financial event contracts, crypto derivatives included, could stay live in all 50 states even if the Supreme Court rules against sports event contracts. Read that again, because it is the strategic heart of the announcement. Robins still says sports betting is the better product. He is not abandoning it. He is building a revenue line that survives a court decision that could gut the sports prediction business overnight.
One thing floating around this story deserves to be left where it belongs. The idea that Bitcoin’s four-year cycle implies a bottom and a fresh bull run, lifting contract volume with it, is a forecast, not a fact. It is a reasonable thing for an analyst to say and a terrible thing for anyone to act on.
Event contracts versus the sports bets you already place
Both involve picking an outcome and risking money on it. Everything structural about them differs, which is why the comparison is worth laying out line by line.
| Feature | Sports bet at a licensed sportsbook | Event contract on a prediction market |
|---|---|---|
| Structure | Fixed-odds wager against the house | Binary contract traded against other participants |
| Who sets the price | The operator’s trading team | The order book, moving with supply and demand |
| Exiting early | Cash out only if, and at the price, the operator offers | Sell the position at market price before expiry |
| Settlement | Operator pays from its own book at the posted odds | Contract resolves at full value or zero against a reference |
| Operator’s cut | Built into the odds as margin or hold | Trading and settlement fees |
| Primary regulator | State gaming commission | CFTC, as a derivatives market |
| Where complaints go | Your state regulator | The exchange and federal channels |
The exit mechanism is the difference bettors underrate. A parlay is locked once it is placed unless the book grants you a cash-out. A contract can be sold back into the market at any time the market is open, which sounds like freedom and in practice means more decisions, more often, in less time.
Who regulates this, the CFTC or your state gaming board?
Event contracts are offered under federal commodities law, overseen by the Commodity Futures Trading Commission, not by state gaming regulators. Operators list them on designated contract markets, which is why these products have appeared in states with no legal sportsbook at all. State regulators and attorneys general dispute that framing, arguing the products are gambling and require state licensing.
Where it has been contested
The fighting so far has centred on sports, not crypto. Kalshi has been in and out of court with state regulators over sports event contracts, including its lawsuit against Louisiana over the CFTC-versus-state question, and Utah went further and filed criminal charges against the company’s founders. Robins himself flagged the possibility of the Supreme Court weighing in on sports event contracts.
Here is where I will commit to a reading. Both sides of the legal argument are serious, and the states’ case against sports contracts is stronger than the industry likes to admit: a contract on who wins a football game has no plausible hedging purpose for anyone. But a contract on the price of Bitcoin is a commodity price derivative, which is the thing federal commodities law was written to cover. I expect crypto event contracts to survive the regulatory fight that sports event contracts might not, and I think that is precisely why DraftKings is building there. That does not make a five-minute Bitcoin market a hedging tool. Functionally, for a retail user, it is a bet with a ticker symbol, and the critics who say so are not wrong about the behaviour even if they are wrong about the law.
Not a one-off: the whole sector is pushing here
DraftKings is late to this, not early. Kalshi and Polymarket’s US arm already run short-duration crypto markets, Polymarket down to five-minute Bitcoin contracts, and Robinhood has leaned into non-sports prediction markets as a growth area. The pattern behind all of it is the same: sports contracts carry legal risk and seasonal demand, financial contracts carry neither to the same degree. If you want the background on how these venues work alongside conventional books, our explainer on how prediction markets differ from sports betting covers the plumbing.
What a bettor should actually check before trying this
Stop asking whether it is legal in your state and start asking which protections travel with the product. That is the shift. A state-licensed sportsbook sits inside a framework you may have come to rely on without noticing: a regulator that takes complaints, mandated responsible gambling tools, and in many states a self-exclusion list that actually blocks your account. A CFTC-regulated contract traded through a brokerage relationship does not plug into that machinery. Your dispute route is the exchange and federal channels, and self-exclusion from your state’s sportsbooks does not necessarily stop you opening a prediction market position.
Three practical points, honestly stated. Availability is broader than sports betting, but it is contested, and an operator can pull markets in a given state on short notice if enforcement pressure lands. Tax treatment of derivatives trading is not the same as tax treatment of gambling winnings, and the correct move there is a conversation with a tax professional rather than a forum thread. And the product itself is new enough at DraftKings that the routing, fees and market structure may all change; the Crypto.com arrangement might not be permanent.
On risk, the short duration is the part to respect. A five-minute binary market lets you take twelve positions an hour, and each one is a complete loss or a full payout with nothing in between. Crypto prices are volatile, the outcome is independent of your reasoning on any single round, and no amount of chart reading changes the fact that fees and spread come out of the pot over time. Set a loss limit before you open an account, treat the money as spent, and use the time-out and limit tools wherever they exist. If gambling has stopped being entertainment, the National Problem Gambling Helpline is free and confidential at 1-800-522-4700, now branded as 1-800-MY-RESET.
What is still open: whether the Supreme Court takes a sports event contract case and how it rules, whether DraftKings brings crypto volume in house and on what terms, and whether state regulators decide to challenge price-based contracts the way they have challenged sports ones. None of that is settled. Anyone telling you otherwise is selling something.